Robert Kiyosaki: 5 Money Mistakes That Keep You Working Forever
The Rich Dad Channel
2,290 views • yesterday Save 23 min 5 min read
Video Summary
Most people believe being broke is a financial issue, but it's actually a mindset problem, according to Robert Kiyosaki. He argues that simply earning more money won't solve it, as people often increase their spending to match their higher income, remaining perpetually broke. Kiyosaki introduces five lessons taught to rich kids that are often missed by those from less affluent backgrounds. These lessons emphasize that true wealth is measured in time—the number of days one can live without working—rather than income. He challenges conventional wisdom, stating that income alone doesn't make you rich and that your primary residence is typically a liability, not an asset, as it takes money out of your pocket. Furthermore, he asserts that savers are "losers" in the current economic climate due to inflation devaluing currency, and that the rich leverage debt to acquire assets that generate income, while the poor and middle class use debt to acquire liabilities.
Short Highlights
- Wealth is Measured in Time, Not Money: True wealth is the number of days you can survive without working while maintaining your standard of living.
- Income Alone Doesn't Create Wealth: A higher salary often leads to increased spending and debt, not financial freedom.
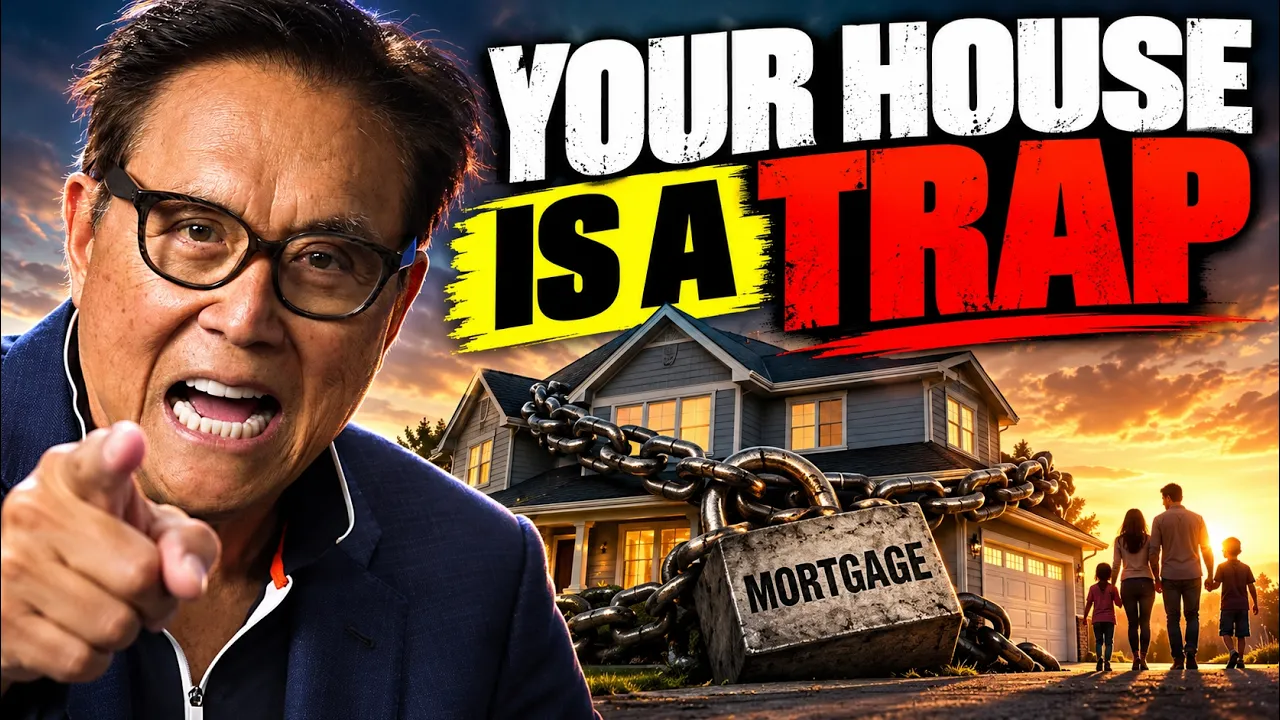
- Your House is Likely a Liability: An asset puts money in your pocket; a liability takes money out. Most homes require ongoing expenses.
- Savers Are "Losers" in Today's Economy: Inflation erodes the value of saved currency, making it essential to own real assets.
- Understand Good Debt vs. Bad Debt: The rich use debt to acquire income-generating assets, while the poor use it for consumption.
- Shift from Working for Money to Having Money Work for You: Focus on building businesses and investments (B and I quadrants) rather than just trading time for money (E and S quadrants).
- Education is Key to Financial Freedom: Understanding the rules of money and investing is more crucial than motivation.
Related Video Summary
Key Details
Lesson 1: Income Doesn't Make You Rich [00:01:39]
- The common belief that a bigger paycheck leads to wealth is a misconception.
- Increased income often results in higher taxes and increased spending, leading to a cycle of being "broke at a higher level."
- True wealth is defined by time, specifically the number of days one can live without working while maintaining their current lifestyle.
"Wealth is measured in time, not money."
Lesson 2: Your House Is Not an Asset [00:04:44]
- A simple definition of an asset is something that puts money in your pocket, while a liability takes money out.
- A personal residence, with its mortgage, taxes, insurance, and repairs, is typically a liability because it consistently drains funds.
- The "American Dream" of homeownership can trap individuals in debt for decades, benefiting the bank rather than the owner.
"An asset puts money in your pocket. A liability takes money out of your pocket."
Lesson 3: Savers Are Losers [00:07:46]
- In the current economic system, saving dollars leads to a loss of purchasing power due to inflation.
- Since 1971, the dollar has not been backed by gold, allowing governments to print more, devaluing existing currency.
- Savers are taxed on interest earned, even as their money loses value, making them lose twice.
"The saver is running up a down escalator. Working harder just to stay in the same place."
Lesson 4: Work on the Right Side of the Cash Flow Quadrant [00:11:22]
- The left side of the cash flow quadrant (E for Employee, S for Self-employed) involves trading time for money and has limitations.
- Employees rely on a job for security, which is often temporary, while self-employed individuals often own a job rather than a business.
- The right side (B for Business owner, I for Investor) is where the rich make money while they sleep by building systems and having money work for them.
"The E and the S work for money. The B and the I have money work for them."
Lesson 5: Debt Can Be Your Best Friend or Worst Enemy [00:15:37]
- There are two types of debt: bad debt, which takes money out of your pocket (e.g., credit cards for consumer goods), and good debt, which puts money in your pocket and is paid for by someone else (e.g., a mortgage on a rental property).
- The rich use debt strategically to acquire assets that generate income, while the poor and middle class often use it for liabilities.
- Understanding the difference and learning to use debt wisely is crucial, as it's a powerful tool that requires education.
"Good debt. Someone else pays it off."
The Power of Time and Education [00:19:35]
- The biggest mistake young people make is not starting their financial education early enough.
- Mistakes made while young are smaller and provide valuable learning experiences, allowing for compounding asset growth over time.
- Ignorance, not age, is the true barrier to financial freedom; the clock starts when education and action begin.
"Ten years from now, you will be standing on one side of a line. Most people never notice which side they're on until it's too late to cross."
The System is Designed for the Rich [00:23:32]
- The financial system, including education, is designed by the rich for the rich to maintain their advantage.
- There are different sets of rules for those who work for money and those who control it.
- Learning the "real rules" of the game is the only effective form of rebellion and the key to playing the game successfully.
"The system was never broken. It was built this way."